
Protect what
you’ve built.
How do you balance growth potential, predictability, and access to your savings? Explore the benefits and tradeoffs of fixed indexed annuities.
Explore fixed indexed annuities
Retirement income. Protection. Possibility.
Explore fixed indexed annuities and retirement income options with Amanda Barber—so you can approach the years ahead with greater clarity and confidence.
A personal conversation. Clear explanations. Room to decide.
A thoughtful place to begin
You’ve spent years building your savings. Now it’s time to understand how they can support the life you want to live.
How do you balance growth potential, predictability, and access to your savings? Explore the benefits and tradeoffs of fixed indexed annuities.
Explore fixed indexed annuitiesWhat will retirement look like when your paychecks stop? Explore income choices and the options for an old 401(k).
Consider income optionsWhat matters most to you: protecting loved ones, flexibility, or cash value potential? Get to know indexed universal life (IUL) insurance.
Explore IUL insuranceFixed indexed annuities, explained simply
Interest credited to your fixed indexed annuity stays in the contract and can earn additional interest over time—the benefit of compounding. Your principal and credited interest are protected from losses caused by market declines.
Protection applies to market declines; withdrawals and applicable charges can reduce contract value.
Guarantees are subject to the insurer’s claims-paying ability. Early withdrawals may reduce the amount you receive.
Your goals come first
Good questions make room for a meaningful conversation. Start wherever you are today.
How are you approaching your financial future, and what feels clear—or still uncertain?
What would you like the next five to ten years to look like? What matters most about getting there?
What feels in the way? If nothing changed, how might that affect your goals? Let’s explore options together.
Have you talked about what financial security would look like for the people who depend on you?
Explore family protection ↗How do your business protection and personal priorities fit together as your business grows?
Explore business considerations ↗Simple steps. Personal attention.
Share your timeline, priorities, and questions. What would feeling more secure in retirement look like for you?
Explore insurance solutions, how they work, and where they may—or may not—fit your needs.
Review the details, ask more questions, and decide at your own pace. There is room to think it through.
A person in your corner
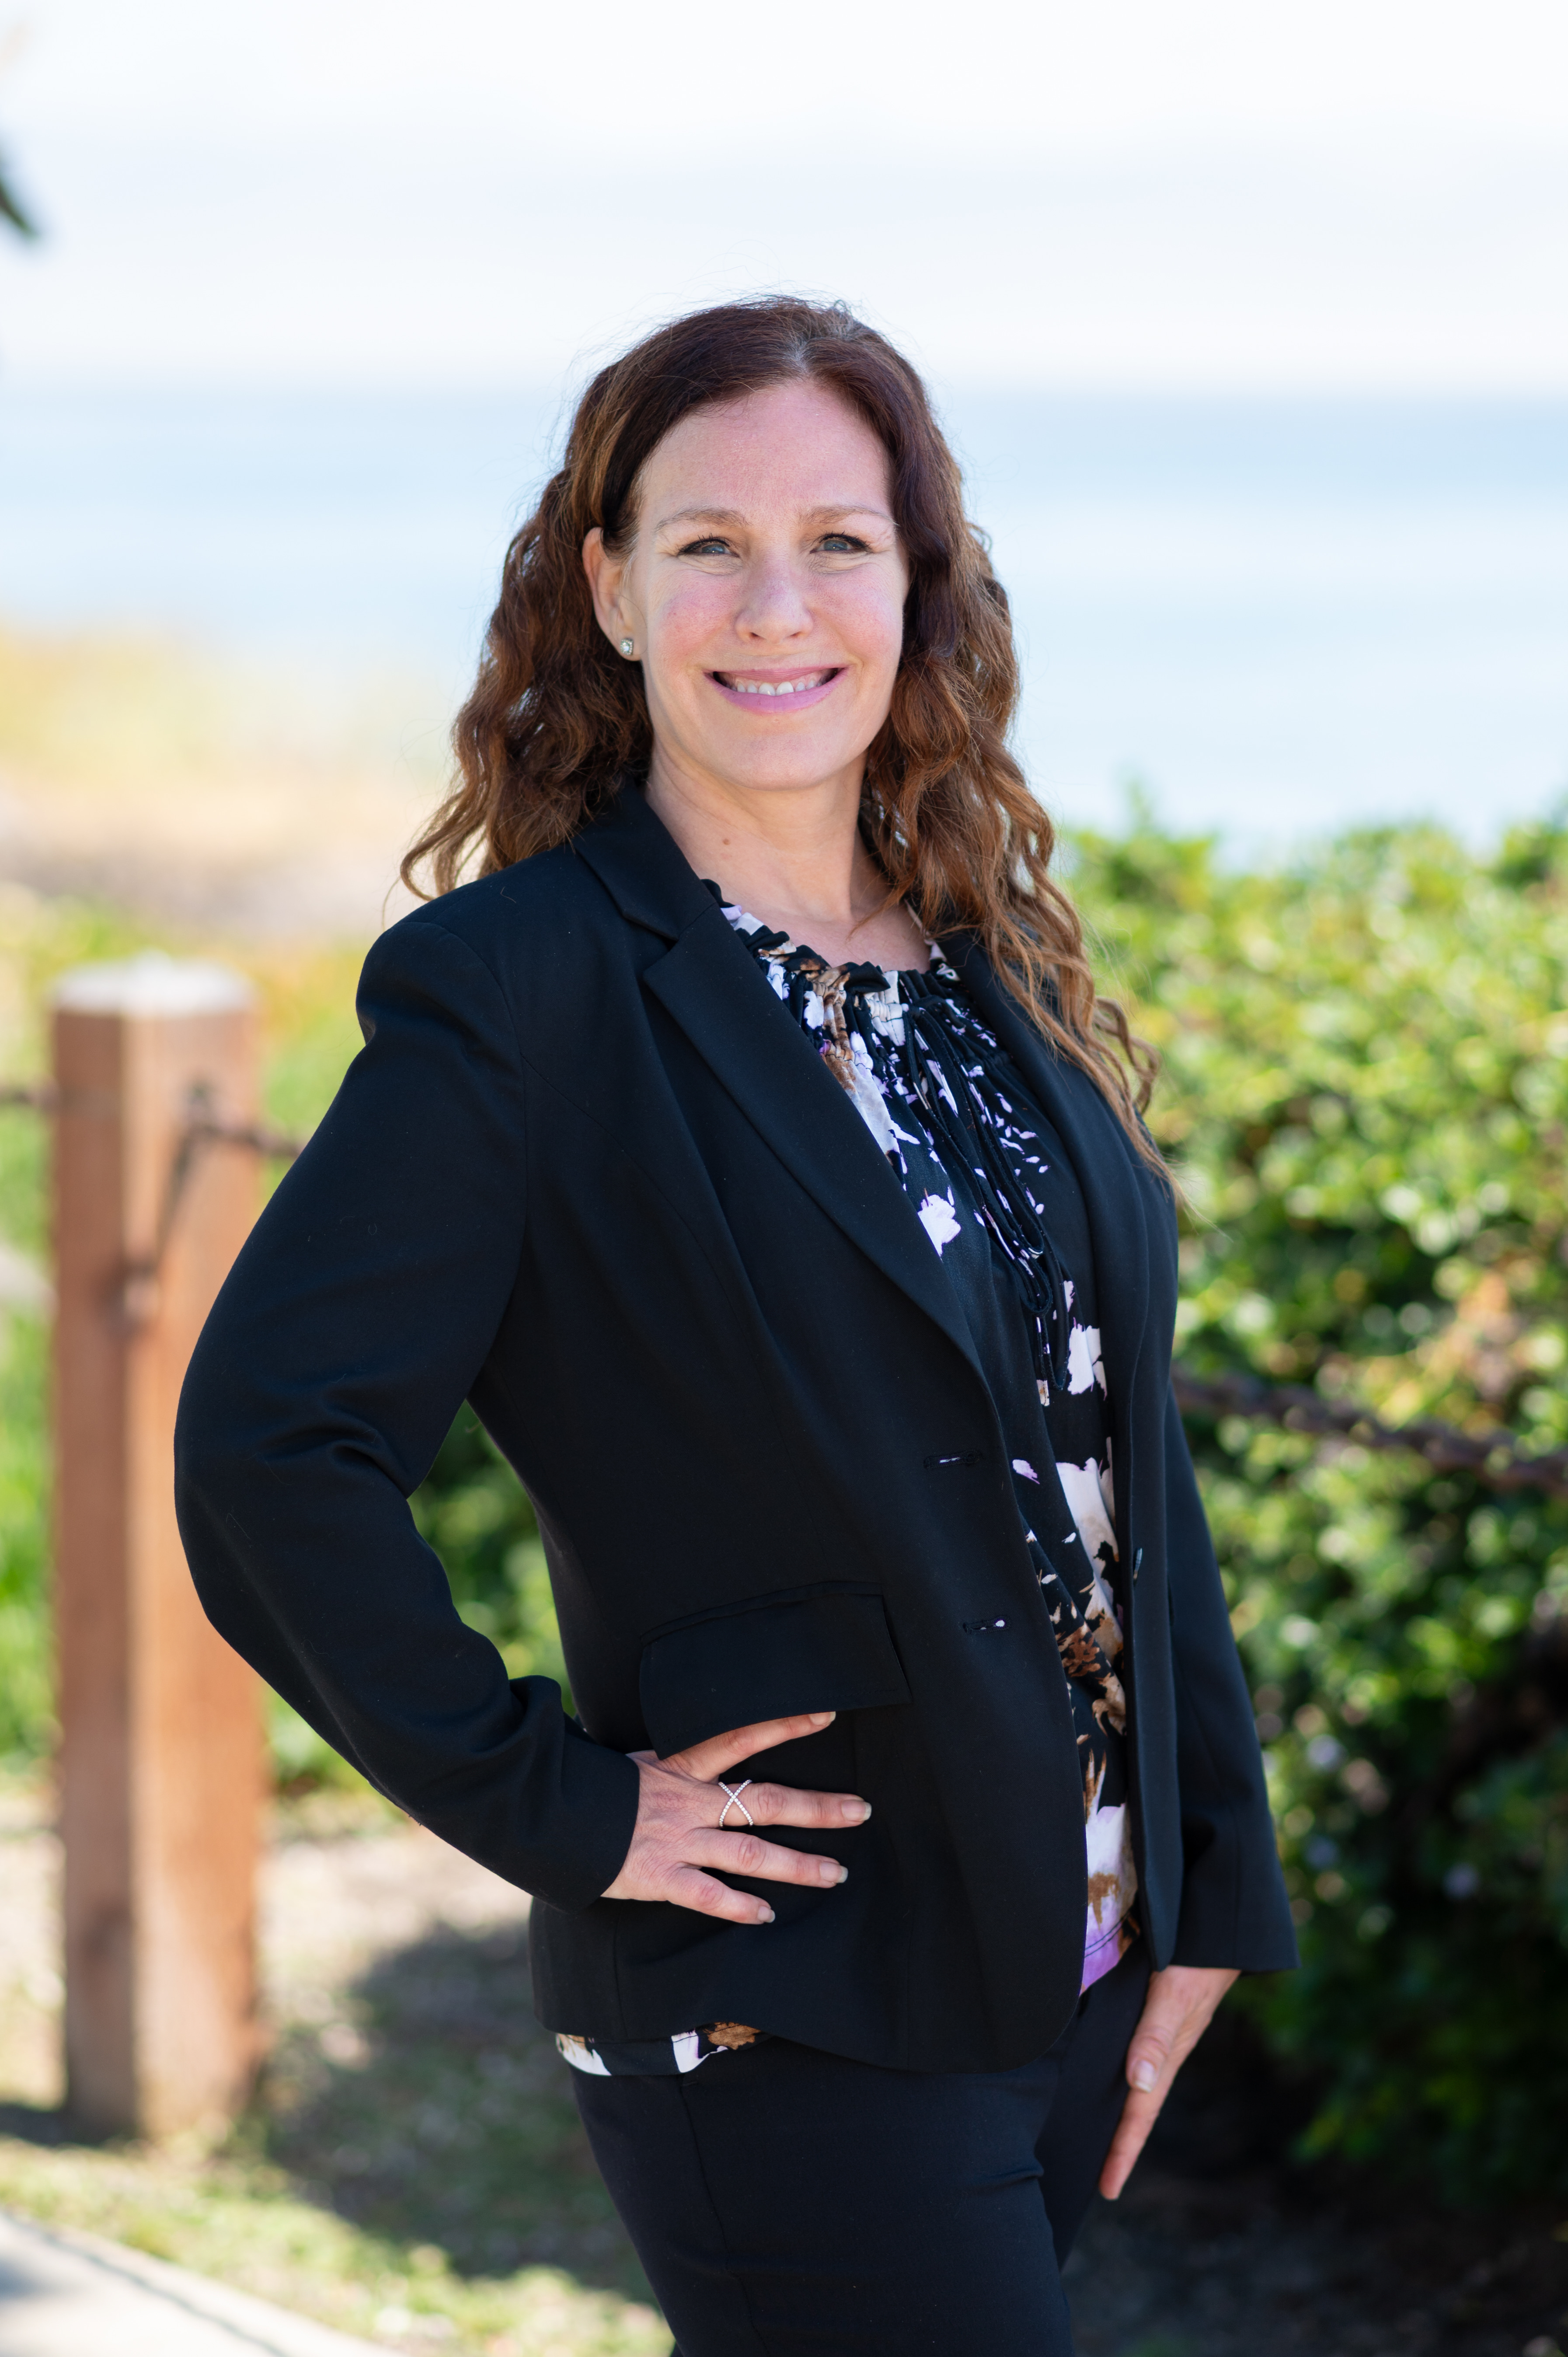
Life Insurance Producer · Global Financial Impact
Retirement is personal. Your conversation should be, too. Amanda helps you explore fixed indexed annuities, retirement income options, and life insurance generational wealth protection—including IUL—with your priorities at the center. Have an old 401(k)? That can be part of the conversation, too.
Start with the questions you have today. Build a clearer understanding of the choices ahead.
Good questions deserve clear answers
A few things you may be wondering
before we talk.
A fixed index annuity offers growth potential through interest linked to an index such as the S&P 500, subject to the contract’s crediting rules. Interest left in the contract can compound over time. Depending on the income option selected, it can also provide a pension-like income stream. Your principal and credited interest are protected from market declines; withdrawals and applicable charges can reduce contract value. Guarantees depend on the issuing insurer’s claims-paying ability.
Access depends on the contract. Some annuities permit a limited amount of withdrawals without a surrender charge. Larger or earlier withdrawals may trigger surrender charges, a market value adjustment, taxes, or reductions in benefits. Keep money for emergencies and near-term expenses accessible outside a long-term annuity.
No. A CD is a bank deposit; an annuity is an insurance contract. Their protections, tax treatment, access to funds, and income features differ. Annuities are not FDIC-insured. Insurance guarantees depend on the issuing insurer’s claims-paying ability.
We start with what matters to you: your retirement timeline, the income you want, and the questions on your mind. Amanda can explain insurance options and their tradeoffs. You do not need to decide on a product during that conversation.
Amanda’s current state list is Arizona, California, Colorado, Florida, Georgia, Hawaii, Michigan, Missouri, North Carolina, New Mexico, Ohio, Oklahoma, Oregon, Texas, Virginia, Washington, and West Virginia. Specific products and services depend on licensing, carrier appointments, and availability in your state.
Bring your questions. Explore your options. Take the next step at your pace.